401(k) Calculator: How Much Will You Have at Retirement?
Enter your age, salary, contribution rate and employer match. This 401k calculator projects your balance at retirement, separates your money from your employer’s, applies the 2026 IRS contribution limits and estimates the monthly income your savings could provide.
Your 401(k) details
How to Use This 401k Calculator
- Age and retirement age: the years left to save. 67 is the full Social Security retirement age for anyone born in 1960 or later.
- Current balance and salary: find these on your latest 401(k) statement and pay stub.
- Contribution rate: the percentage of each paycheck you defer.
- Employer match: a common formula is “50% of your contributions up to 6% of salary.” Enter 50 and 6. For a dollar-for-dollar match up to 4%, enter 100 and 4.
- Return and raises: the expected average yearly investment return and pay increase.
The 401k calculator updates instantly and shows how much of your future balance comes from you, your employer and market growth. It also automatically caps contributions at the 2026 IRS limits for your age.
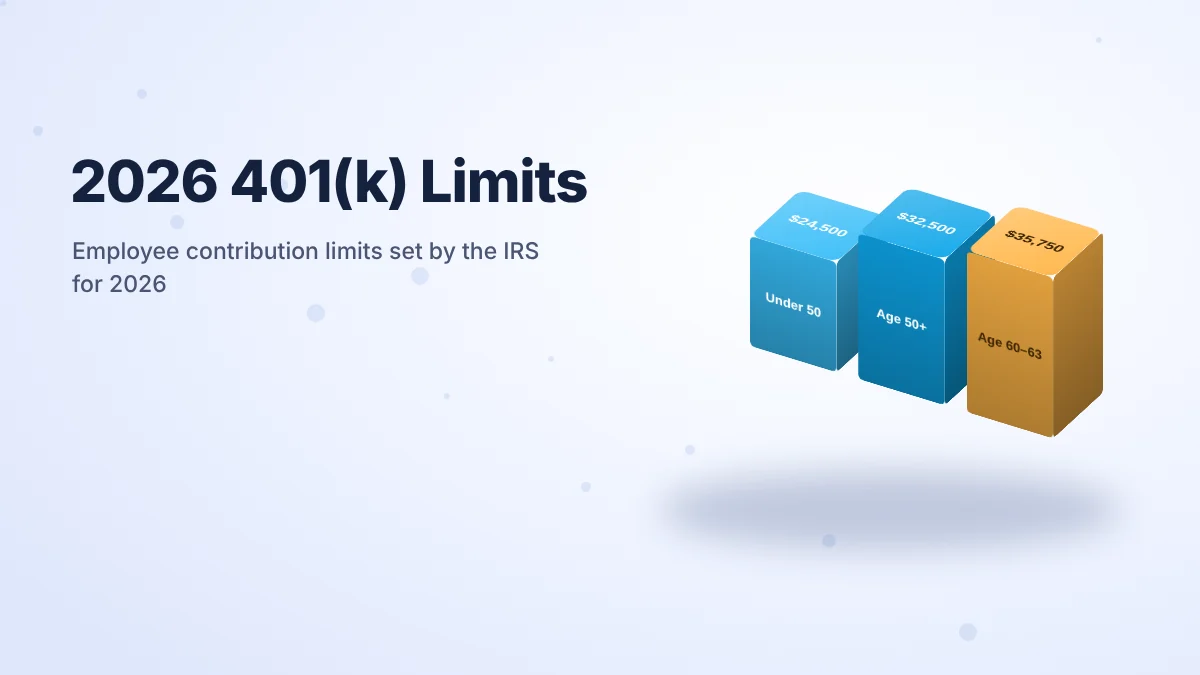
2026 Limits Built Into the 401k Calculator
| Limit (2026) | Amount |
|---|---|
| Employee elective deferral | $24,500 |
| Catch-up contribution, age 50+ | +$8,000 (total $32,500) |
| “Super” catch-up, ages 60–63 | +$11,250 (total $35,750) |
These limits were announced by the IRS in November 2025 and apply to 401(k), 403(b) and most 457 plans. Employer matching contributions don’t count toward your $24,500 employee limit. Starting in 2026, higher earners (roughly those whose prior-year FICA wages exceeded $150,000) must make catch-up contributions on a Roth basis. Our calculator holds future limits at 2026 levels, though the IRS usually raises them with inflation.
How a 401(k) Employer Match Works
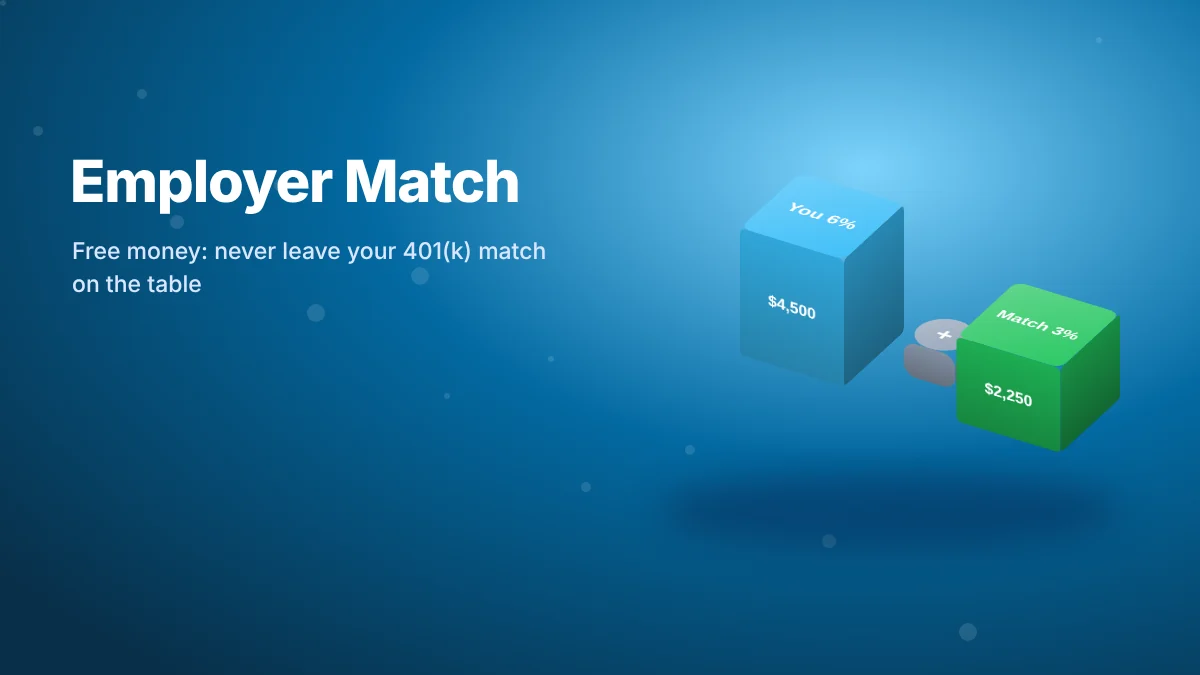
An employer match is part of your pay that you only receive if you contribute. With a salary of $75,000 and a “50% up to 6%” match:
- You contribute 6%, which is $4,500
- Your employer adds 50% of that, which is $2,250
- That’s an instant 50% return before any investment growth
Contribute 3% instead and you’d get only $1,125 from your employer, leaving $1,125 a year on the table. Use the 401k calculator with match settings to see how that gap grows over decades. Also check your plan’s vesting schedule: matched money may take a few years before it fully belongs to you.
How Much Should You Have in Your 401(k)?
A 401k calculator shows where you’re heading, but it helps to compare against common benchmarks too.
Many retirement planners suggest these savings milestones, measured as a multiple of your salary across all retirement accounts:
| Age | Common target |
|---|---|
| 30 | 1× salary |
| 40 | 3× salary |
| 50 | 6× salary |
| 60 | 8× salary |
| 67 | 10× salary |
These are rules of thumb, not requirements. Your target depends on when you retire, your expected spending, Social Security, a pension, and other savings. If you’re behind, raising your contribution by 1% each year is a painless way to catch up. Test it in the 401k calculator by bumping your contribution rate.
How Much Monthly Income Will My 401(k) Provide?
The 401k calculator uses the 4% rule: withdraw about 4% of your balance in the first year of retirement, then adjust for inflation. Historically, that rate has given a high chance of the money lasting around 30 years. A $1,000,000 balance supports roughly $40,000 a year, or about $3,333 a month, before taxes. Withdrawals from a traditional 401(k) are taxed as ordinary income.
Traditional vs Roth 401(k)
Traditional 401(k)
Contributions lower your taxable income now. You pay income tax on withdrawals in retirement.
Roth 401(k)
Contributions are made after tax. Qualified withdrawals, including growth, are tax-free.
Which is better?
Roth often wins if you expect a higher tax rate later. Traditional often wins if your tax rate is high today.
Saving outside work too? Our Roth IRA calculator projects tax-free growth in an individual account.
Early Withdrawals and Penalties
Taking money out before age 59½ usually triggers ordinary income tax plus a 10% early withdrawal penalty, with some exceptions such as the “Rule of 55” for workers who leave their job in or after the year they turn 55. A $20,000 early withdrawal in a 22% tax bracket could cost about $6,400 in taxes and penalties. Required minimum distributions (RMDs) generally begin at age 73.
Disclaimer: this 401k calculator is for educational purposes. Projections assume a constant return and aren’t guaranteed. They exclude fees, taxes and inflation, and contribution limits beyond 2026 are assumed unchanged. This is not financial, tax or investment advice.
401k Calculator FAQs
How much can I contribute to my 401(k) in 2026?
$24,500, plus an $8,000 catch-up if you’re 50 or older. Workers aged 60 to 63 can add $11,250 instead, for a total of $35,750.
How does the 401k calculator handle employer match?
It multiplies your contribution, up to the match limit percentage of your salary, by your employer’s match rate, and adds the result to your account every year.
Is this 401k calculator free?
Yes. It’s free, needs no sign-up, and runs entirely in your browser.
What rate of return should I use?
Many planners use 5% to 7% for a diversified stock and bond portfolio over the long run. Use a lower rate if you invest conservatively or are close to retirement.
How long will my 401(k) last in retirement?
Using the 4% rule, savings have historically lasted about 30 years. Higher withdrawals or poor early market returns shorten that.
Does this 401k calculator include taxes?
No. It shows pre-tax balances. Traditional 401(k) withdrawals are taxed as income, while qualified Roth 401(k) withdrawals are tax-free.